
It's the classic homeowner dilemma: sell your current home first, or buy the next one first? In the Inland Empire's 2026 market, the answer is more nuanced — and more favorable — than it's been in years. Here's how I walk my clients through the decision.
The Case for Selling First
Maximum buying power. You know exactly what you netted, so you can shop with confidence and make stronger, non-contingent offers.
No double mortgage. Carrying two housing payments in a ~7% rate environment is expensive and stressful.
Cleaner negotiations. Sellers prefer buyers who already sold — in competitive pockets of Rancho Cucamonga and Upland, a "must sell first" contingency can still cost you the house.
The Case for Buying First
You only move once. No temporary rentals, no storage units, no crashing with family.
Today's market is kinder to contingent offers. With 43–56 median days on market across Rancho Cucamonga, Upland, and Ontario, sellers are more open to sale contingencies than they were during the frenzy years.
You can negotiate from strength. If your current home is in a desirable area, a bridge loan or HELOC on your existing equity can fund the down payment while you sell on your own timeline.
The Middle Path Most People Miss
You don't have to choose between chaos and limbo. Strategies that work well in this market:
Sell with a rent-back agreement. Close the sale, then rent your own home back from the buyer for 30–60 days while you buy. Common and widely accepted right now.
Buy contingent on your sale closing. Far more viable in today's balanced inventory than it was two years ago.
Use a HELOC or bridge financing. Tap your equity for the down payment, buy first, then sell — best for homeowners with strong equity and stable income.
List and shop simultaneously with a coordinated close. An experienced listing agent can time both transactions to close days apart — this is where a top Inland Empire Realtor earns their fee.
Ontario Ranch growth, prices, and what buyers and sellers should do this fall.
Upland housing market update for September 2026: median prices, days on market, and buyer/seller tips from Lou Armendariz, a top-rated Realtor serving Upland, Rancho Cucamonga & the Inland Empire. Call (909) 816-1328.
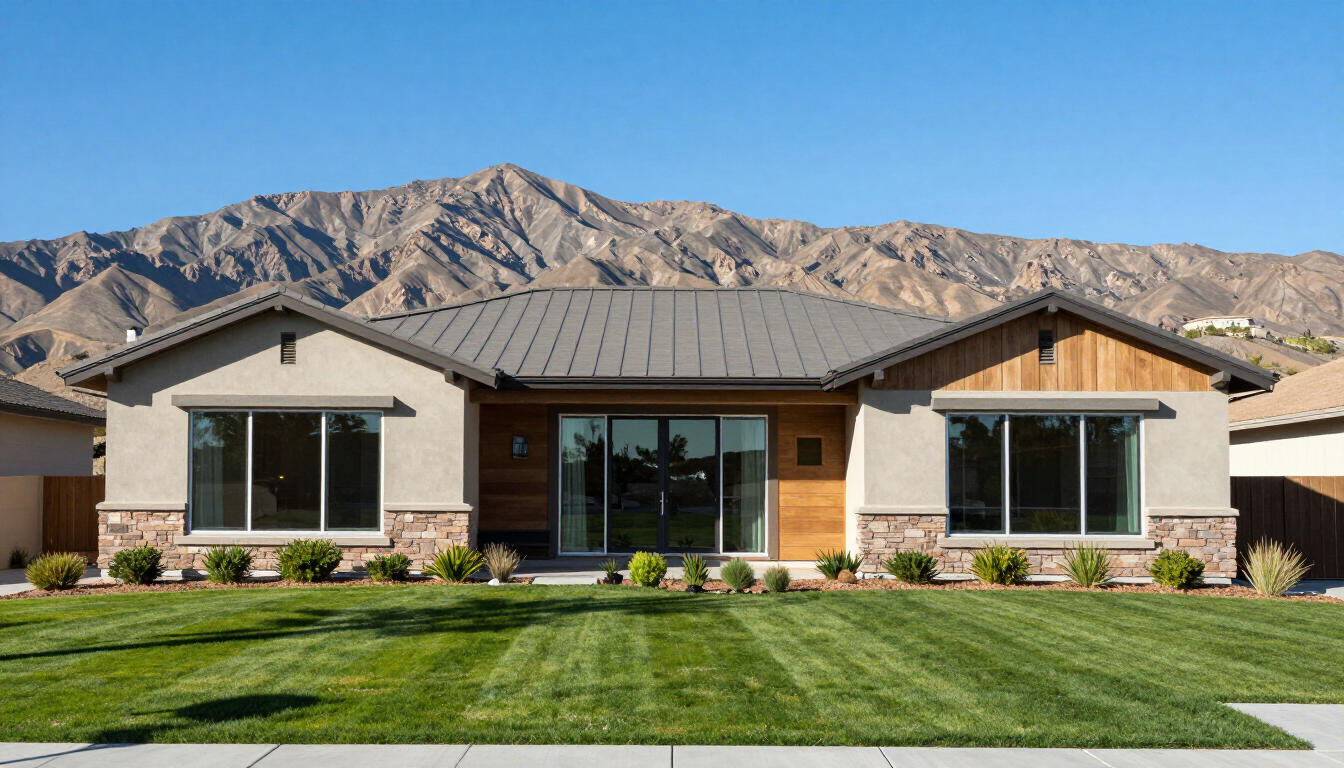
Welcome to the Inland Empire! As your dedicated realtor in Inland Empire, we help first-time buyers find perfect homes in Riverside and San Bernardino counties with expert local guidance.
Frequently Asked Questions About the Upland Housing Market
Is Upland CA a buyer's or seller's market right now?
Upland is in balanced-to-warm territory. With ~43 median days on market and growing inventory, buyers have negotiating power they haven't had in years — but accurately priced homes still sell well, so sellers remain in a fair position.
What is the median home price in Upland, CA?
As of September 2026, the median listing price in Upland is approximately $823,000–$827,500, or roughly $457 per square foot.
Is now a good time to buy a house in Upland?
For buyers planning to stay 5+ years, yes. Prices are stable, inventory gives you choices, and you can negotiate terms that were impossible during the frenzy years. Waiting for a major price drop isn't supported by the data.
How long does it take to sell a house in Upland?
The median is about 43 days from listing to pending. Well-priced, well-presented homes move faster; overpriced homes linger.
What This Means for You
Upland is in a healthy, balanced stretch: stable prices, reasonable timelines, and fair negotiating conditions on both sides. Whether you're moving up within the city or planting roots here for the first time, fall 2026 is a genuinely workable market — and having the right Realtor in Upland makes all the difference.
Thinking about a move in Upland? Call or text Lou Armendariz at (909) 816-1328 or email Thatguylou@onewestrealty.com for a free, no-pressure market consultation.
Louis (Lou) Armendariz, Realtor® | DRE #02198506 | One West Realty, DRE #01303106 — serving Upland, Rancho Cucamonga, Ontario & the Inland Empire.